A colored contact lens distributor buys a product for RM12 per pair and offers it to local retailers for RM22. The difference looks generous enough to build a profitable business.
Then a retailer asks for RM20.
The request seems reasonable. It’s only RM2 less, and the customer promises to order more if the distributor agrees.
But how much more would the customer need to buy? Would a larger shipment reduce the distributor’s expenses enough to justify the discount? And if the retailer plans to sell through Shopee or TikTok Shop, will the product still leave enough money after marketplace fees and promotions?
These are the questions that make wholesale pricing more complicated than adding a percentage to a supplier quotation.
A workable wholesale price must cover the distributor’s costs while leaving a realistic commercial opportunity for the retailer.
This guide follows a hypothetical colored contact lens distributor serving beauty retailers in Malaysia. We’ll calculate its costs, build a wholesale quotation, examine a price negotiation, and see how different selling channels affect the decision.
All prices, quantities, and business scenarios below are illustrative. They are not UYAAI quotations, actual customer transactions, or recommended industry profit margins.
The Supplier’s Price Is Not Your Actual Cost
Let’s start with the distributor’s first purchase.
The business plans to import 1,000 pairs of colored contact lenses for resale to local beauty shops. The supplier offers a price of RM12 per pair.
At that point, the distributor knows the purchase price but not the full cost of making the products available for local sale.
International freight, customs clearance, transportation, and other applicable import expenses may need to be included.
Calculate the Landed Cost per Pair
For this example, the distributor prepares the following estimate:
| Cost Item | Total |
|---|---|
| Product purchase: 1,000 pairs | RM12,000 |
| International freight and insurance | RM1,500 |
| Customs clearance and applicable import costs | RM1,000 |
| Local transport and receiving | RM500 |
| Total landed cost | RM15,000 |
The calculation is straightforward:
Landed Cost per Pair = Total Landed Cost ÷ Saleable Quantity
RM15,000 ÷ 1,000 = RM15 per pair
The supplier’s price was RM12, but the distributor’s estimated landed cost is RM15.
That additional RM3 changes every subsequent pricing decision.
The calculation assumes that all 1,000 pairs are saleable. Any damaged or unsaleable stock would need to be accounted for appropriately. Import duties, tax treatment, and clearance costs must also be confirmed for the actual products, importer, and destination market.
There’s another distinction worth making.
The RM15 represents the estimated cost of acquiring the goods and bringing them into saleable inventory. It does not automatically include everything required to sell them.
The distributor may still incur order-processing expenses, local delivery costs, payment fees, sales commissions, and fixed business overhead.
Those costs will become important when we compare wholesale quotations later.
Why Ordering More Is Not Automatically Cheaper
Suppose the distributor could reduce freight cost per pair by importing twice as many products.
That sounds beneficial, but only if the additional inventory can be sold within a reasonable period.
A lower landed cost is not particularly useful when the remaining stock ties up cash, incurs storage expenses, or becomes difficult to sell.
For this reason, wholesale pricing and inventory planning should inform one another without being treated as the same problem.
If you’re reviewing how purchasing quantities affect working capital, see How to Reduce Cash Tied Up in Slow-Moving Colored Contact Lens Inventory.
For now, our distributor has 1,000 saleable pairs at an estimated landed cost of RM15 each.
The next question is how much to charge retailers.
Set a Wholesale Price Using Margin, Not Guesswork
The distributor initially considers selling at RM22 per pair.
That produces RM7 in gross profit before additional selling expenses.
But two commonly confused calculations can describe this result differently.
Markup = (Selling Price − Cost) ÷ Cost × 100
Gross Margin = (Selling Price − Cost) ÷ Selling Price × 100
Using RM15 as the landed cost and RM22 as the wholesale price:
- Markup: RM7 ÷ RM15 = 46.7%
- Gross margin: RM7 ÷ RM22 = 31.8%
The markup is higher because it measures profit against cost. Gross margin measures profit against revenue.
A distributor that adds 30% to cost does not achieve a 30% gross margin.
To calculate a selling price from a target gross margin, use:
Selling Price = Unit Cost ÷ (1 − Target Gross Margin)
For example, a target gross margin of 30% on an RM15 cost gives:
RM15 ÷ 0.70 = RM21.43
This doesn’t mean that 30% is the correct margin for colored contact lenses. It is simply an example of how the calculation works.
The distributor still needs to consider whether the resulting price covers its business expenses and whether retailers can sell the product profitably.
In our scenario, RM22 becomes the initial wholesale quotation.
It is a starting decision, not a guaranteed profitable selling price.
Does the Retailer Have Enough Room to Make Money?
The distributor is now discussing a first order with an independent beauty shop.
The retailer is considering a consumer selling price of RM39 per pair.
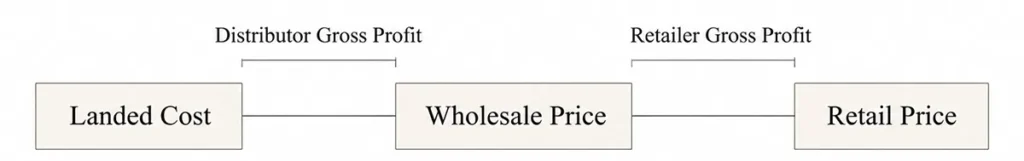
At an RM22 wholesale purchase price, the retailer’s calculation looks like this:
| Retail Pricing Item | Amount |
|---|---|
| Purchase price from distributor | RM22 |
| Assumed retail selling price | RM39 |
| Gross profit per pair | RM17 |
| Gross margin | 43.6% |
The retailer appears to have RM17 of gross profit on every pair sold.
But it still needs to pay the expenses involved in making those sales.
An independent beauty shop may incur rent, staff costs, payment processing fees, advertising expenses, and other operating costs. Some may be largely fixed, while others change with sales volume.
A gross margin of 43.6% therefore does not mean that 43.6% of revenue becomes net profit.
The retailer must also decide whether RM39 is a realistic selling price for its customers.
A higher theoretical margin has little value if the product rarely sells.
That is why distributors should consider the retailer’s commercial situation rather than calculating their own profit in isolation.
A product can offer attractive wholesale margins and still be difficult to distribute if retailers cannot sell it at viable prices.
The initial numbers look workable for both businesses.
Then the retailer asks for a discount.
A RM2 Discount Changes More Than the Selling Price
The beauty shop wants to reduce the wholesale price from RM22 to RM20 per pair.
The distributor’s landed cost remains RM15.
At the original price, gross profit is RM7 per pair. At the proposed lower price, it falls to RM5.
The selling price has declined by 9.1%, but gross profit per pair has declined by 28.6%.
For a 100-pair order, that’s a difference of RM200 in gross profit.
There is a further cost that the distributor must account for: fulfilling the customer’s order.
Suppose the distributor expects RM120 in delivery and order-handling costs, plus RM40 in other directly attributable selling and payment expenses for a 100-pair order.
These figures are hypothetical, but they allow us to distinguish product gross profit from the amount left after fulfilling the order.
Calculate Order Contribution, Not Just Gross Profit
For this example:
Order Contribution = Wholesale Revenue − Landed Cost of Goods Sold − Direct Order Expenses
At RM22 per pair:
| Order Calculation | Amount |
|---|---|
| Revenue: 100 × RM22 | RM2,200 |
| Landed cost of goods | − RM1,500 |
| Product gross profit | RM700 |
| Delivery and order handling | − RM120 |
| Other direct selling expenses | − RM40 |
| Order contribution | RM540 |
That RM540 is available to help cover fixed overhead and operating profit.
It is not final net profit.
Now reduce the wholesale price to RM20, keeping the other assumptions unchanged.
The order generates RM2,000 in revenue and RM500 in product gross profit.
After RM160 of direct order expenses, the contribution falls to RM340.
The distributor gives up RM200 of contribution for the same order quantity without receiving any operational benefit in return.
That is a significant concession.
But what if the retailer genuinely increases its purchase quantity?
Compare the Deal the Customer Is Actually Offering
The retailer now proposes purchasing 200 pairs in one shipment if the distributor agrees to a lower price.
Suppose the direct expenses for this consolidated 200-pair order would be RM210 rather than the RM320 required to handle two separate 100-pair orders.
The distributor can compare the following options:
| Order Scenario | Revenue | Direct Order Expenses | Order Contribution |
|---|---|---|---|
| A: 100 pairs at RM22 | RM2,200 | RM160 | RM540 |
| B: 100 pairs at RM20 | RM2,000 | RM160 | RM340 |
| C: 200 pairs at RM20 | RM4,000 | RM210 | RM790 |
| D: 200 pairs at RM21.50 | RM4,300 | RM210 | RM1,090 |
| E: Two separate 100-pair orders at RM22 | RM4,400 | RM320 | RM1,080 |
All scenarios assume a landed product cost of RM15 per pair. They exclude fixed overhead and any extra financing or inventory-holding costs.
These numbers lead to a more interesting decision than simply accepting or rejecting a discount.
Scenario C generates RM790 in contribution, more than one 100-pair order at the original price. If those extra 100 pairs represent genuinely additional profitable sales, it could be attractive.
However, if the retailer would otherwise have placed two 100-pair orders at RM22, Scenario C is considerably less profitable than keeping the original terms.
Scenario D offers another possibility.
At RM21.50 per pair, the distributor gives the retailer a small unit-price reduction in exchange for a confirmed consolidated 200-pair purchase.
Under the assumed expense structure, that order generates RM1,090 in contribution, slightly more than two separate 100-pair orders at RM22.
The difference is only RM10. Any extra financing cost, delayed payment, additional handling, or change in the cost assumptions could eliminate that advantage.
Still, the calculation reveals something useful: the value of a discount depends on what the buyer commits to in return.
The Distributor’s Decision
The distributor keeps RM22 as the standard quotation for a 100-pair order.
For a confirmed consolidated order of 200 pairs, it is willing to consider RM21.50, provided the projected expenses and payment conditions remain as assumed.
It does not accept RM20 automatically.
The decision is based on identifiable order economics rather than a belief that every larger customer deserves a discount.
The next step is to confirm whether the retailer’s larger order is firm, whether payment will arrive as agreed, and whether the products can be delivered without additional costs.
One important limitation remains: the spreadsheet cannot prove that the retailer will sell all 200 pairs.
The distributor should consider the customer’s purchasing history, expected sell-through, and inventory commitment before treating a larger order as a commercial success.
Different Sales Channels Change the Pricing Calculation
The same colored contact lens may be sold by an independent beauty shop, an optical retailer, or an ecommerce seller.
Their selling expenses can be very different.
This is especially relevant when a distributor supplies both physical retailers and sellers operating through Southeast Asian marketplaces.
Physical Beauty and Optical Stores
For a physical beauty shop, retail profitability depends partly on the cost of maintaining a storefront and serving customers.
The retailer may invest in product displays, staff training, customer acquisition, and ongoing service.
These costs don’t all appear on the individual product invoice, but the business must recover them through its overall sales.
The distributor should therefore understand the type of store it is supplying.
A retailer serving customers who value convenient access, appropriate product information, and in-person assistance may evaluate products differently from a seller competing primarily through online promotions.
However, the distributor should not assume that every physical store can sustain a higher retail price.
Local demand and competing offers still matter.
Shopee, Lazada, and TikTok Shop Sellers
An online seller may have lower storefront overhead but face marketplace-related deductions.
These can include commissions, transaction fees, promotional expenses, seller-funded discounts, fulfillment costs, and other applicable charges.
The amounts vary by marketplace, seller program, category, and country.
For example, Shopee Malaysia’s terms describe category-dependent commission rates. TikTok Shop Malaysia also maintains category-specific fee schedules and revised its Marketplace and Mall commission structures effective October 31, 2026.
Relevant official references include Shopee Malaysia’s Terms of Service and TikTok Shop Malaysia’s Seller Academy.
These policies are not interchangeable, and the rates applying to one seller may not apply to another.
A seller should check the current fees and product eligibility in its own account rather than relying on a general percentage found in an article.
Return to the RM22 wholesale price.
Suppose an online retailer sells the product for RM35, but its actual combined marketplace deductions are RM6 and its order-level fulfillment and handling expenses total RM3.
The contribution calculation becomes:
RM35 − RM22 − RM6 − RM3 = RM4 per pair
The RM6 and RM3 amounts are illustrative combined expenses, not published marketplace fee rates.
For this seller, RM35 may look attractive in a product listing but leave limited room for further advertising, losses, and overhead.
The distributor cannot fix every online seller’s economics through lower wholesale prices.
However, understanding those economics helps distinguish an unrealistic price request from a genuine channel-cost problem.
Our guide to How to Sell Colored Contact Lenses on Shopee, Lazada, and TikTok Shop Without Competing Only on Price explores the wider sales strategies available to marketplace businesses.
What Happens When Online Prices Undercut Physical Stores?
Imagine the beauty shop sells the lens for RM39 while an online retailer advertises it for RM35.
The physical retailer may ask the distributor to stop other sellers from offering lower prices.
That request should not be answered by immediately imposing a mandatory resale price.
First, the distributor should establish whether the two offers are truly comparable.
The online price may reflect a temporary voucher, different fulfillment conditions, seller-funded promotional spending, or a product variation.
The retailer’s actual transaction price and expenses are more informative than the headline listing alone.
Resale-pricing restrictions also raise legal concerns.
Malaysia’s Competition Commission identifies resale price maintenance, including minimum resale prices, as a competition-law concern. Even recommended prices can raise issues if they become a mechanism for restricting independent pricing.
See the Malaysia Competition Commission’s Guidelines on Chapter 1 Prohibition.
Distributors should not assume they can require independent retailers to maintain a fixed price or punish them for selling below a recommendation. Market-specific legal guidance is appropriate when designing resale-pricing policies.
A more useful commercial response is to understand each channel’s cost structure, ensure product offers are comparable, and negotiate wholesale terms that reflect legitimate purchasing and service conditions.
How to Prepare a Wholesale Price Sheet
The Malaysian example gives us a process that can be used for other products and markets.
The distributor does not need a complicated pricing system to begin. A spreadsheet can be sufficient, provided it distinguishes confirmed costs from assumptions.
The following structure can be copied into a pricing worksheet.
| Field | Example or Calculation |
|---|---|
| Product / SKU | Selected colored contact lens |
| Order quantity | 100 pairs |
| Supplier unit price | RM12.00 |
| Allocated import and acquisition costs | RM3.00 per pair |
| Landed cost per pair | RM15.00 |
| Planned wholesale price | RM22.00 |
| Gross profit per pair | RM7.00 |
| Gross margin | 31.8% |
| Order revenue | RM2,200 |
| Landed cost of goods sold | RM1,500 |
| Direct order expenses | RM160 |
| Order contribution | RM540 |
| Assumed retail selling price | RM39.00 |
| Retailer gross margin | 43.6% |
| Quotation conditions | Quantity, payment, delivery, validity |
| Review trigger | Cost change, customer discount request, or channel-cost change |
Five Questions to Answer Before Sending a Quote
Once the worksheet is complete, the distributor should be able to answer five practical questions.
1. What does each saleable pair actually cost?
Use confirmed acquisition and import costs, not only the supplier’s advertised unit price.
2. How much gross profit does the proposed wholesale price generate?
Calculate both the amount per pair and the gross margin. Do not confuse markup with margin.
3. How much contribution remains after fulfilling the order?
Deduct the direct expenses associated with processing, delivering, and collecting payment for the transaction.
4. Can the retailer make a viable business out of the product?
Use realistic retail selling-price assumptions and the retailer’s relevant channel expenses. A distributor should understand the economics without attempting to control independent resale prices.
5. What conditions would justify changing the quotation?
A larger committed quantity, lower fulfillment cost, or improved payment terms may change the economics. A vague promise of future purchases is not the same as a confirmed order.
These answers form the basis for an initial commercial decision.
They do not eliminate the need to review customer demand, regulatory requirements, or actual sales performance.
Know When to Recalculate
A wholesale price sheet should not be completed once and forgotten.
Update it when acquisition costs change, shipment terms are revised, selling expenses increase, or customer order patterns materially change.
A regular review can be useful, but a significant cost or transaction change should trigger a recalculation immediately.
Keep the dates and assumptions visible so old estimates are not mistaken for current quotations.
For businesses preparing supplier discussions, What to Ask Before Requesting a Colored Contact Lens Price List explains which product and order details should be clarified before comparing offers.
A Profitable Price Must Survive the Actual Order
Our Malaysian distributor began with a straightforward calculation: RM15 in landed cost and a proposed RM22 wholesale selling price.
The retailer’s discount request revealed why that calculation alone was not enough.
Reducing the price to RM20 would sharply reduce contribution on a 100-pair order. A larger consolidated purchase could change the economics, but only when the savings and extra sales were real.
The distributor ultimately had a defensible reason to keep RM22 for smaller orders and consider RM21.50 for a confirmed larger purchase under the assumed conditions.
The exact prices are not the lesson.
The useful method is to calculate the real acquisition cost, estimate order-level contribution, consider the retailer’s economics, and test any discount against what the buyer actually commits to.
A wholesale price is sustainable when it works beyond the first quotation.
Request a UYAAI Wholesale Price List
If you are planning to distribute branded colored contact lenses, reliable product and quotation information is the starting point for building your own pricing model.
UYAAI supplies colored contact lenses for wholesale and distribution, with a standard branded-wholesale starting MOQ of 100 pairs and a minimum of 5 pairs per SKU for applicable orders.
You can explore the UYAAI Wholesale Catalog to review available product categories and styles.
To request pricing, share your destination country, business type, sales channel, intended order quantity, and the product styles or replacement cycles you are interested in.
Our team can provide relevant product and wholesale quotation information for your business to evaluate.
Your final selling prices should reflect your own verified costs, local market conditions, applicable regulations, and commercial responsibilities.